
81%
Fragmentation Is the Operating Reality
Of 428 leaders interviewed across both waves are not on a single unified system.
428 Interviews, Two Waves – the research points to a clear shift in how organizations buy HR, payroll, and HCM technology: the category is moving from feature evaluation to burden evaluation. The next step leaders want: routine decisions made by company policy, with people reviewing the exceptions.
In June 2026, G2 published The New Buying Logic for HR and Payroll, based on 211 interviews with leaders responsible for HR and payroll technology. In September and October 2026, G2 ran a second wave: 217 new interviews at US organizations, with the same questions and two new ones on routine workforce decisions. This report reads both waves together, 428 interviews in all. Where both waves asked a question the same way, the two results appear side by side.
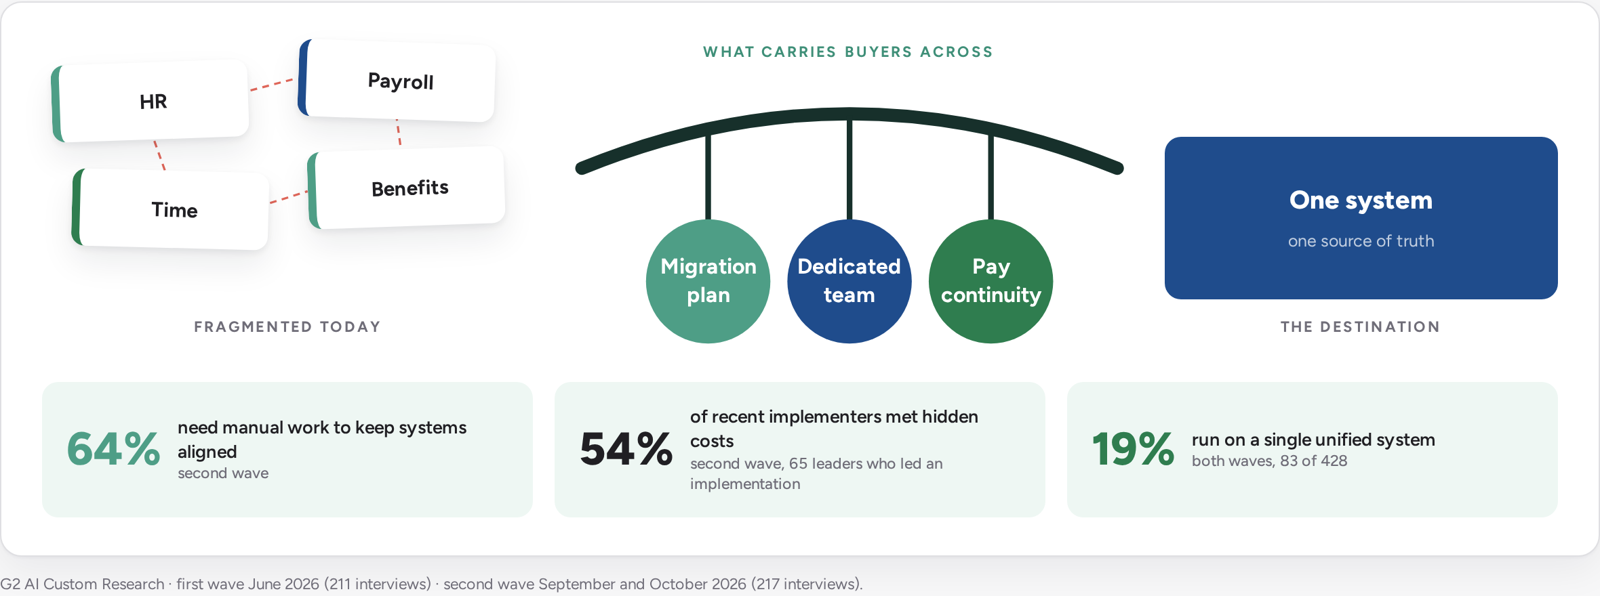
Together, the two waves show that HR software and payroll software buying decisions are no longer shaped mainly by product features; they are shaped by operating burden. Across 428 interviews, 81% of organizations are not on a single unified system. In the second wave, two in three hold people data in two or more systems and 64% still need manual work to keep HR and payroll aligned, so manual reconciliation is the starting condition for evaluation.
As a result, buyers assess vendors through a broader lens. In both waves, about eight in ten define value in terms of total cost, including implementation, services, and ongoing support, and 74% of second-wave leaders strongly prefer or consider essential a dedicated contact who knows their account. Switching is feasible but heavy: of second-wave leaders who recently led an implementation, 54% met at least one hidden cost.
Trust is built through control. 86% of second-wave leaders put reliability and predictability ahead of new AI features, and trust grows with proof: accuracy demonstrated over time and approval checkpoints with human override. Where compliance exposure exists, it sits in fragmented setups: 24% of leaders in fragmented environments feel exposed, against none on a unified system.
The two new questions point to a clear next step. At 62% of organizations, managers spend a few hours or more each week on routine workforce decisions, and 77% of leaders agree those decisions should be automated whenever company policy clearly defines the outcome. Only 24% have done it. The implication is clear: organizations will embrace change, but only when the move reduces fragmentation, lowers transition burden, and preserves oversight at every step.
Of 428 leaders interviewed across both waves are not on a single unified system.
Of second-wave leaders would welcome one unified system for HR and payroll, rising to 87% among those in fragmented setups.
Take a broad total-cost view that includes support and services, not just subscription price, in both waves.
Of second-wave leaders agree routine HR and payroll decisions should be automated when company policy defines the outcome. Only 24% have done it.
Most organizations still run HR and payroll across more than one system, and manual work is what keeps them aligned. Across 428 interviews, 81% are not on a single unified system. This operational friction is the baseline shaping how buyers evaluate HR and payroll technology, and it is the root cause they feel everywhere else.
“From my experience, having everything in one system is much easier. It's a lot cleaner. Things operate smoother. Changes and modifications are instantaneous. It's always the preferred method to have things done.”
— Payroll Manager, communications
rely on fully manual synchronization and reconciliation
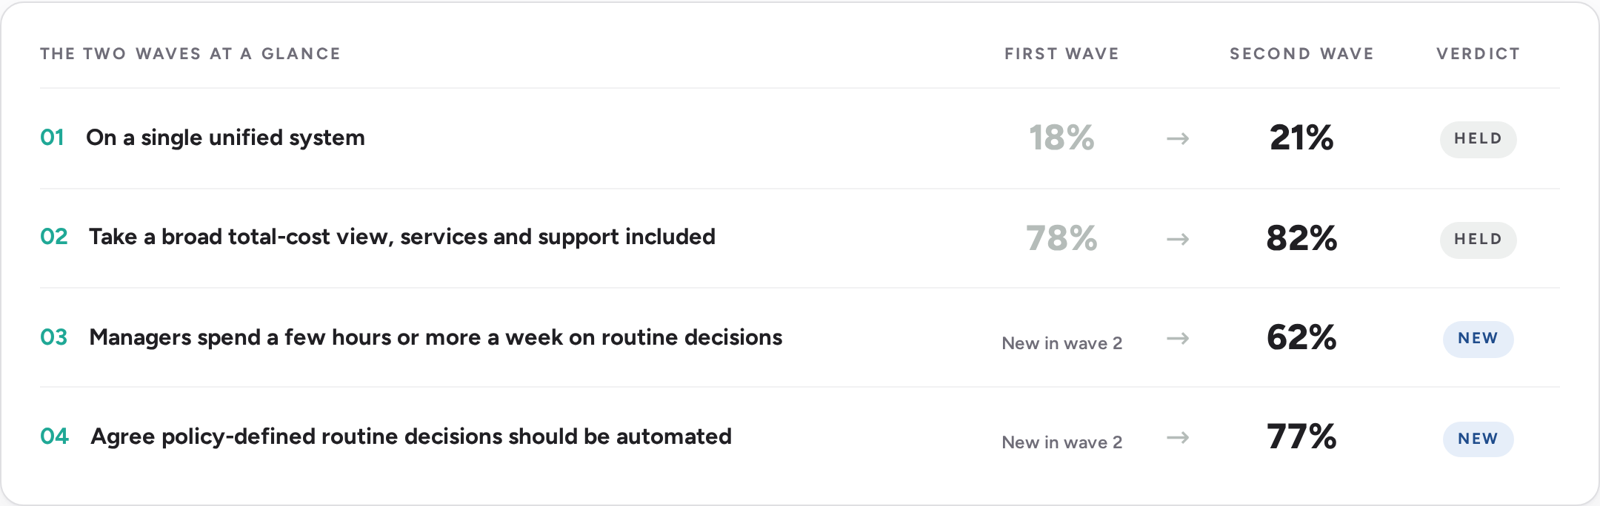
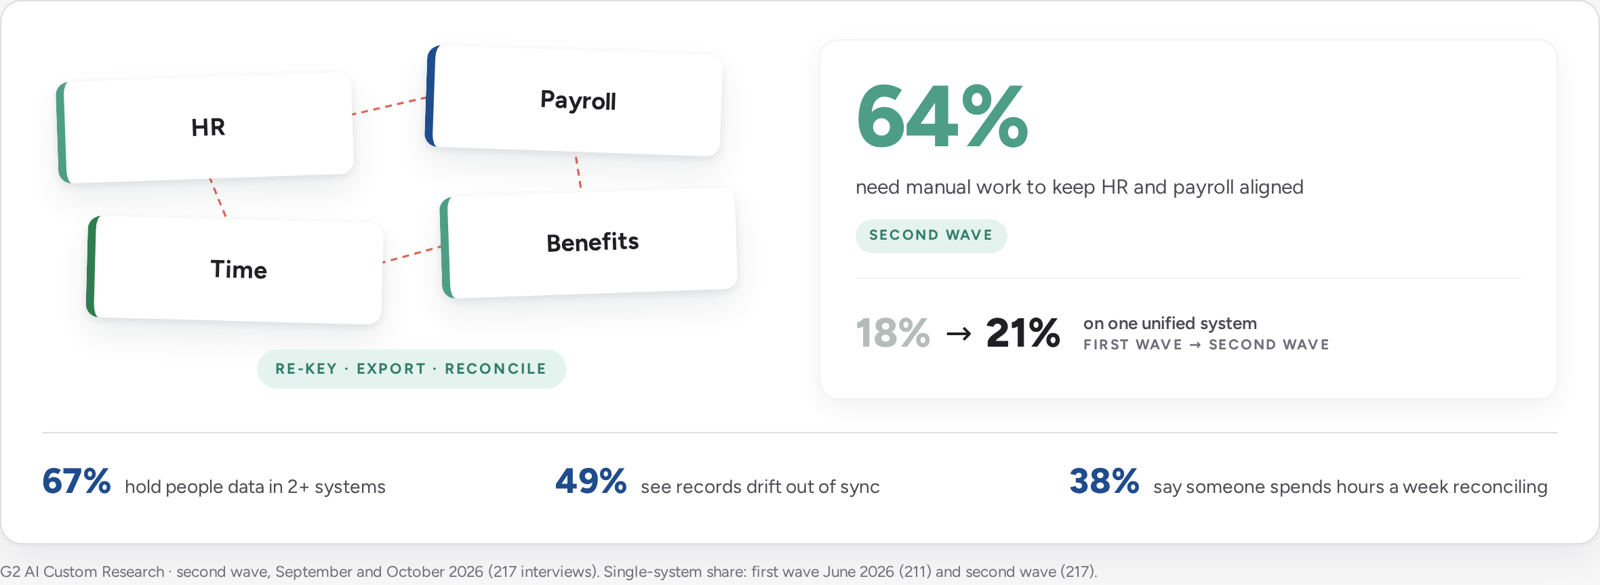
Fragmentation is the norm, not the exception. Across both waves, about one in five run on a single unified system, 18% in the first wave and 21% in the second. In the second wave, two in three organizations (67%) hold people data in two or more systems, and 64% need some manual work to keep HR and payroll aligned: 33% rely on manual synchronization and reconciliation, and 31% have mostly automated syncs that still leave manual exceptions.
The seams show up in day-to-day work. Nearly half of second-wave leaders (49%) see records drift out of sync at least occasionally, and at 38% of organizations someone spends a few hours or more every week reconciling data between systems. First-wave leaders described the same tax in concrete terms: applicant tracking that does not talk to time and attendance, payroll that does not feed benefits, records re-keyed by hand between tools that were never designed to connect. Before buyers weigh features or price, they are already absorbing the cost of moving data between systems, and that burden is the lens through which they evaluate anything new.
Manual work still holds systems together: 64% of second-wave leaders need manual work to keep HR and payroll in sync, from re-keying changes to checking records between payroll cycles. At 38% of organizations it takes a few hours or more every week.
Only about one in five run on one system: 19% of the 428 leaders operate on a single unified system. The rest are managing the gaps between tools, which means most buyers already feel the pain that consolidation would remove.
Fragmentation is the opening, not an obstacle to work around. If you are evaluating HR management software or payroll software, the goal is not one more tool bolted onto a crowded stack; it is a way out of the reconciliation tax. Keep the destination in view: one unified HR platform, one source of truth, no manual handoffs. The fragmented status quo is the strongest argument for HR software consolidation, and most of the market already feels it.
“We're pretty good at keeping it aligned. At the expense of one person that is basically focused on that. Which, again, is terrible use of people. That's why I think, going with a system that is integrated and more automated. Would be a big win for us.”
“At least once a month, our information just gets all messed up, and we have to input it again.”
“The real expense of a fragmented back office is the manual work no one prices at purchase. This research puts numbers to what finance leaders feel every close cycle: disconnected systems are a recurring tax, and consolidating onto one is as much a cost decision as an operational one.”
Buyers consistently describe wanting a single system with one source of truth. They frame consolidation as risk reduction, not convenience: fewer integration points, fewer manual touch points, and a smaller surface area to secure. Asked directly in the second wave, 62% would welcome one unified system.
“I think that it would change probably for the better if we had one consistent system. Then it would be less chance of errors between the systems, and make our job easier.”
— Senior Finance Specialist, government
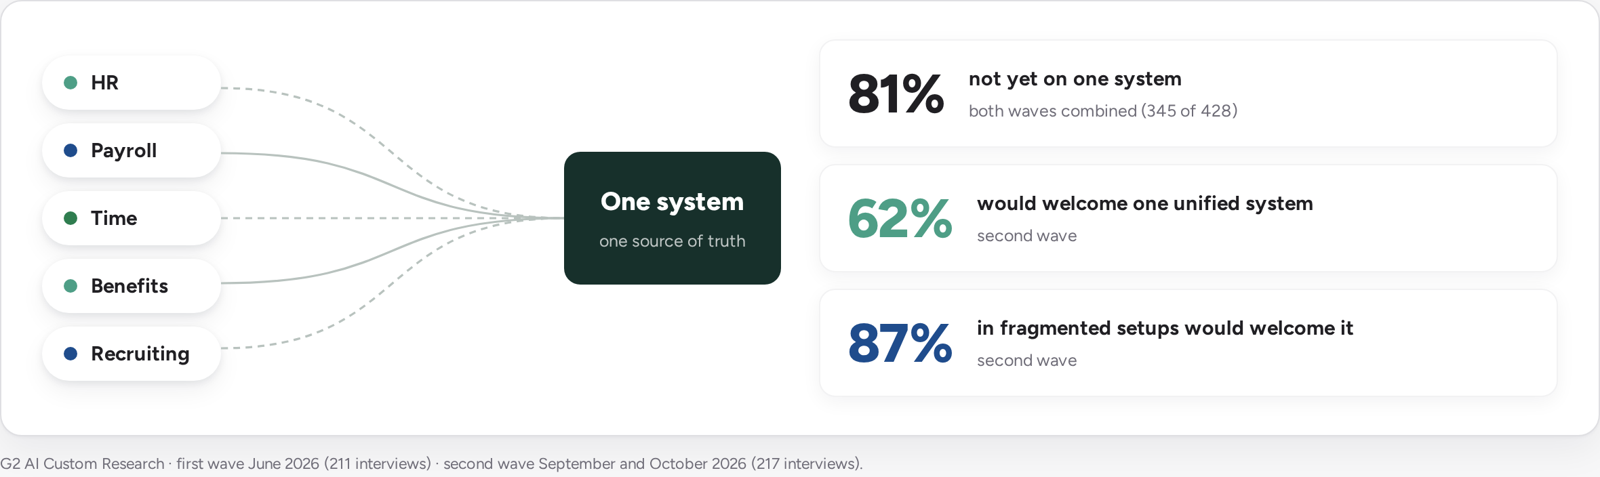
would welcome one unified system for HR and payroll
When leaders describe what they actually want, they do not list features. They describe a single system: one platform, one app, one source of truth, so employees and administrators stop jumping between tools and reconciling data by hand. Across 428 interviews, more than four in five have not reached that state.
The first wave could only infer that demand from how leaders described their target state. The second wave asked directly: 62% would welcome one system (38% outright, 25% with reservations), 30% are already unified or expect little practical change, and only 6% would prefer to keep separate systems. The appeal tracks the pain: 87% of leaders in fragmented multi-system setups would welcome one system, against 58% in partially unified environments. The benefit they name first is concrete: less manual entry, reconciliation, and data movement (40%), ahead of better reporting and visibility (17%), more consistent and secure data (17%), and fewer logins and vendors to manage (16%).
The doubts are specific, not general. 58% raise no major concern about consolidating, while others name concentrated security risk (15%), a single point of failure (14%), or the cost of migration (10%).
One source of truth is the goal: Leaders want HR, payroll, time, and benefits to live in one place so data does not have to be moved, matched, or trusted across systems. 62% of second-wave leaders would welcome one unified system, and only 6% would keep separate systems.
Unified architecture is framed as risk reduction: Buyers connect consolidation to fewer integration points that can break, fewer manual touch points where errors enter, and a smaller surface area to secure and audit. Among the most fragmented, 87% would welcome one system.
Treat consolidation as a risk decision, not a feature list. A single unified system, one database underpinning HR, payroll, time, and benefits, removes manual reconciliation, shrinks the data surface to secure, and eliminates integration breakpoints. Those are the proof points to look for. The second wave's reservations (concentrated security risk, a single point of failure, migration cost) are the questions to put to any vendor, and the journey matters as much as the destination: ask how the move itself will be de-risked.
“So we wanted a solution that would be one platform that covered everything had one app that had all of those pieces in it so the employees didn't have to learn different systems and jump from one system to another to get their daily work done.”
“I generally agree. If our HR and our software were together, that would make those types of decisions automated. But because our systems are separate, we do have separate rules with regards to payroll and HR that are not automated because our systems do not do that. But I strongly agree that would be a good thing if they did.”
“For years, HR and payroll were bought feature by feature. What stands out here is that leaders are done managing the seams between systems. The teams that feel in control are the ones who stopped reconciling by hand and moved to a single source of truth, and that is a people decision as much as a technology one.”
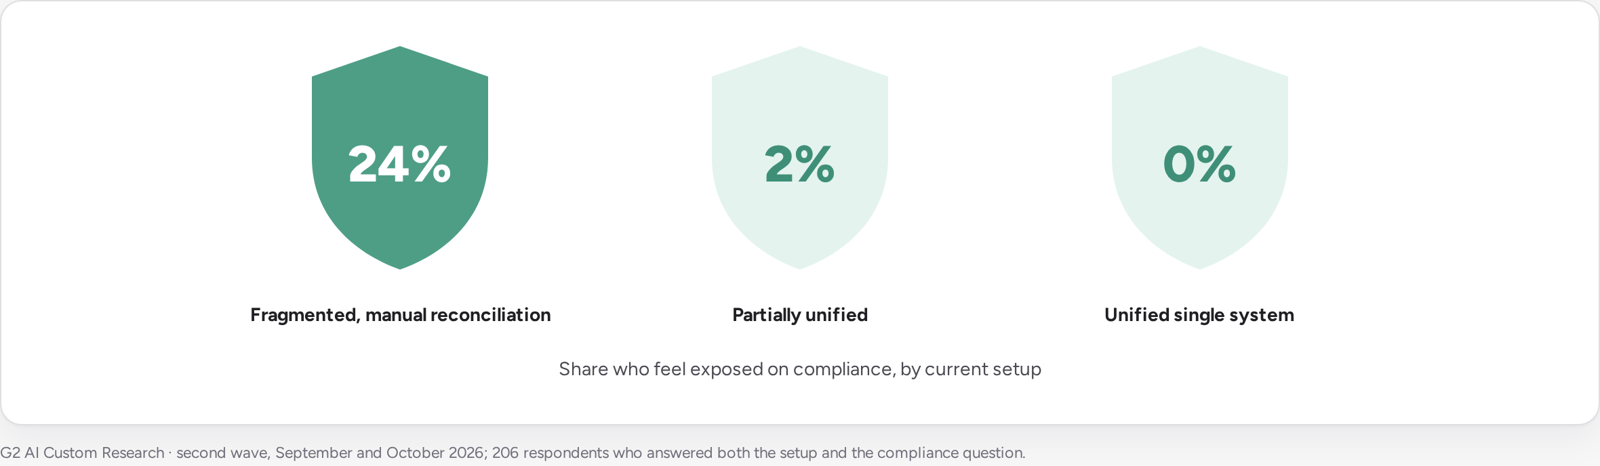
Compliance and security are on every leader's mind, and keeping up takes constant effort. Where leaders feel exposed, fragmentation is the common thread: 24% of second-wave leaders in fragmented setups feel exposed on compliance, against none on a unified single system.
“I am very confident that our organization is meeting all the compliance that is required right now because it's on one system. We have not had any problems, so I'm very confident.”
— Vice President, healthcare
still track at least some regulatory change by hand
Compliance and security were on every leader's mind, and the work of keeping up is constant. In the second wave, 52% of leaders manage compliance across multiple states or countries, 57% still track at least some regulatory change by hand, and 45% have had a compliance scare, close call, or security incident at some point. For many teams, staying compliant depends on people keeping up with every rule change.
Where leaders feel exposed, fragmentation is the common thread. First-wave leaders tied their exposure directly to disconnected data, with every integration a potential point of failure or leak, and the second wave measured it: almost nine in ten of those who feel exposed by manual processes and disconnected tools run fragmented multi-system setups. In that group, 24% feel exposed, against 2% in partially unified environments and none of those on a unified single system, and 19% name manual file transfers, disconnected-system errors, or integrations as their single biggest security risk. Consolidating data reduces the surface area to secure and the places it can go wrong.
Compliance takes constant effort: 57% still track some regulatory change by hand and 52% juggle several jurisdictions. For many, staying compliant depends on people keeping up with every rule change, not on the system handling it.
Fragmentation is the named source of exposure: 24% of leaders in fragmented setups feel exposed on compliance, against 2% in partially unified environments and none on a unified single system. Almost nine in ten of those who feel exposed run fragmented setups.
Compliance and security are universal concerns, but most teams are managing them with manual effort layered over fragmented data. The structural answer is a unified, single-database architecture: one governed source of truth that shrinks the attack surface, keeps data clean for accurate reporting, and turns compliance from a constant manual chase into a built-in property of the system. The second wave's cross-tab is the evidence to weigh: exposure concentrates where data is fragmented and disappears where it is not.
“And then I think that having a lot of disparate systems like my current company does that are semi-connected [or] connected, but there's always going to be the risk of an integration not functioning properly.”
“I'm fairly confident that we're meeting our compliance requirements, but it's something that requires constant attention rather than something we can assume is handled automatically. That confidence comes from regular audits, established payroll controls, compliance reviews, system reporting, and staying current with regulatory changes.”
“The finding that stays with me is that most leaders' confidence in compliance is manual. It holds because people watch it constantly, not because the systems handle it. That is a heavy load to carry, and it is why moving to one unified system reads as risk reduction, not convenience.”
Buyers have moved past subscription price as the measure of value. In both waves, about eight in ten evaluate through a total-cost-of-ownership lens that includes implementation, services, and ongoing support, and dedicated human support is expected as part of the value, not an optional add-on.
“For us, that cost of ownership goes well beyond the subscription fee. We look at implementing your services, integrations and ongoing support and the internal resources required to maintain and optimize the platform over time.”
— Chief Human Resources Officer, technology
strongly prefer or consider essential a dedicated contact who knows their account
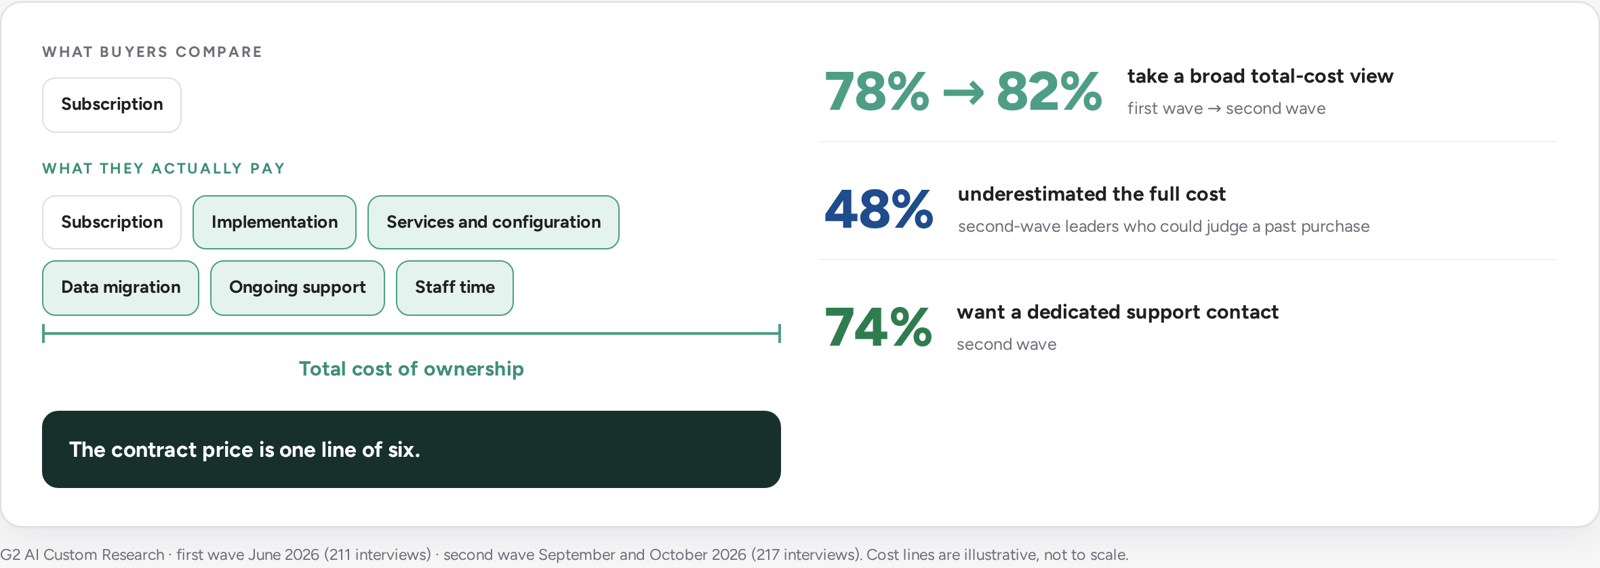
Value decisions are anchored in total cost, not sticker price. About eight in ten leaders take a broad ownership view that includes implementation, services, and ongoing support: 78% in the first wave and 82% in the second. That challenges a common assumption in the category, that buyers ignore services and support when comparing vendors. They do not, because the costs that surprise them arrive after signing: second-wave leaders say buyers most often underestimate ongoing support, maintenance, and paid add-ons (30%) and implementation, configuration, and internal labor (29%), and 48% of those who could judge a past purchase underestimated its full cost.
Alongside cost, buyers expect a relationship. 74% of second-wave leaders strongly prefer or consider essential a dedicated contact who knows their account, and 55% have been through generic support that caused delays, repeated explanations, or a missed payroll-critical issue. Buyers are not just pricing software; they are pricing the effort and risk around it, and the partner who stays after go-live is part of what they are buying.
Total cost of ownership defines value for most: About eight in ten judge value across the full lifecycle: license, implementation, services, configuration, and the internal resources needed to run the platform. The contract price is one line item, not the decision.
Dedicated human support is expected, not a bonus: 74% of second-wave leaders strongly prefer or consider essential a dedicated contact who knows their business, and 55% have been slowed down by generic support. For high-stakes payroll work, the support relationship is part of what buyers are paying for.
Evaluate on total cost of ownership and the support relationship, not subscription price. Make the all-in math explicit: implementation, services, configuration, and ongoing support alongside the license, and ask specifically about the two lines second-wave leaders most often underestimated, paid add-ons and internal labor. Expect dedicated, continuous human support to be a core part of the value, not an add-on, and ask vendors to price it transparently.
“What matters most is continued HR support. And payroll support, dedicated specialists that know my account, know the nature of our business, know the history of any issues or things that may come up.”
“For me, total cost of ownership goes well beyond the software subscription. The license fee is important. But it's often only one component of the overall investment. I would look at implementation costs, consulting, and configuration services.”
“The clearest signal here is that buyers no longer equate price with value. Nearly eight in ten weigh total cost of ownership, the implementation, the services, the ongoing support, over the subscription line. On that math a fragmented stack carries a recurring tax in manual work, and consolidating onto one well-supported system is as much a finance decision as an operational one.”
Switching HR and payroll platforms is feasible but high-stakes, with the fear centered on business disruption: the immediate impact on pay and benefits if anything goes wrong. The second wave put the cost on record: 54% of leaders who recently led an implementation met at least one hidden cost, and vendor support is what made the difference.
“The staff time it takes to switch systems, the amount of money it takes to switch systems. It can just be a big project.”
— Chief Executive Officer, healthcare technology
of recent implementers met at least one hidden cost
Switching HR and payroll platforms is not seen as impossible, but it is seen as high-stakes. The weight comes from what these systems touch: payroll and HR reach every employee, so any transition carries the risk of disrupting pay, benefits, and trust. The first wave described the fear; the second wave asked the people who had been through it. Of the 65 leaders who personally led an implementation in the last few years, 54% met at least one hidden cost, most often consultant, configuration, or support fees (23%), and 49% needed more time, staff, or budget than planned.
The same group shows what tips the balance: 66% say the vendor made migration, setup, or training easier or gave strong hands-on support, against 29% who say the vendor made it harder. Asked what holds them back from a change, second-wave leaders most often say their current system works (33%), followed by the cost of switching (26%) and timing and capacity (19%), and the information they most want before signing is the all-in cost of integrations, services, support, and future fees (31%). Buyers will move, but only when the upgrade clearly outweighs the strain and they trust that the migration itself will be handled.
Hidden costs are common: 54% of recent implementers met at least one hidden cost and 49% needed more time, staff, or budget than planned. What buyers most want before signing is the all-in cost of integrations, services, support, and future fees (31%).
Migration confidence is the unlock: 66% of recent implementers say the vendor made migration, setup, or training easier or gave strong hands-on support. Buyers move when they believe the transition will be managed: a clear plan, a dedicated team, and continuity through go-live.
Switching is a barrier, but the barrier is risk, not impossibility. Make migration confidence a condition of the deal: require a structured implementation program, a dedicated team that owns the move, and explicit continuity safeguards for pay and benefits. Ask for the all-in cost of integrations, services, support, and future fees in writing, because consultant and configuration fees are the hidden cost second-wave implementers met most often. De-risking the move matters as much as choosing the destination.
“The biggest hesitation holding me back is the immense amount of work it takes to make a change, the cost to make a change, the hours to make a change, the investment of time, will we get it right? All of those concerns.”
“It was easier to do than we expected, and allowed us to automate things like payroll approval instead of having to have the bookkeeper prompt someone to approve payroll. So it was automated. It reduced errors a lot. And really streamlined our process.”
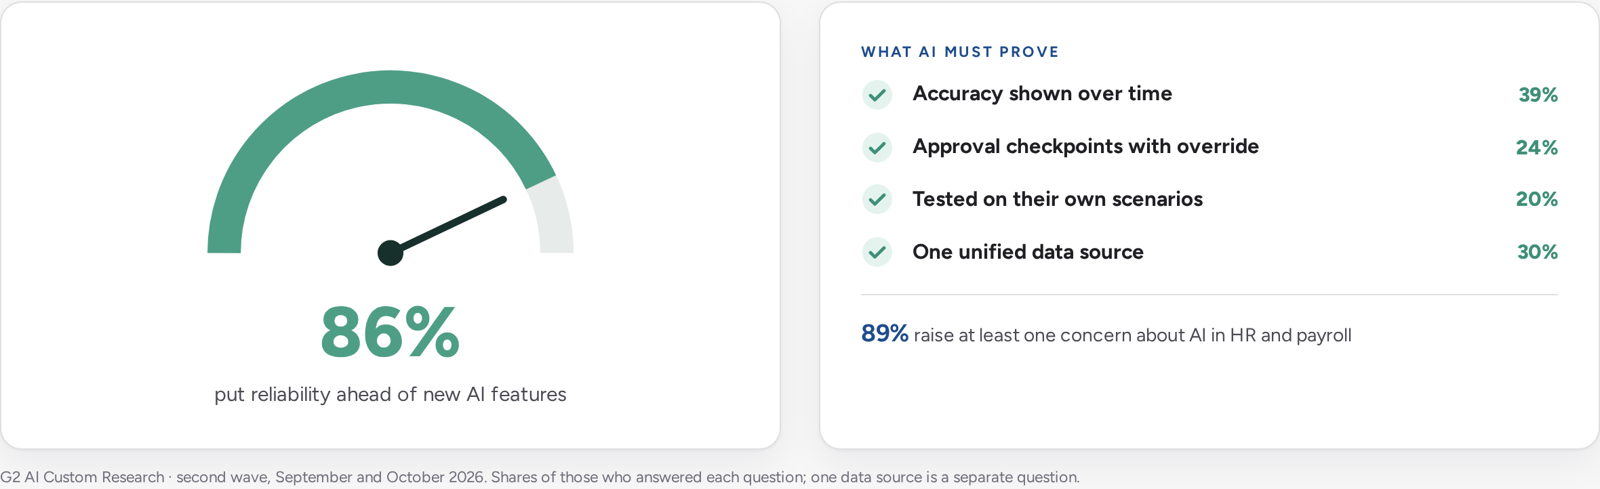
Buyers do not reject AI and automation; they set conditions. In the second wave, 86% put reliability and predictability ahead of new AI features, and 40% name errors and payroll accuracy as their top concern. Trust in automation is inseparable from trust in the data underneath it.
“I would prefer that they draw from one unified data source because whenever you have multiple data sources, it introduces the possibility of uncertainty or error.”
— Director of People and Culture, healthcare
raise at least one concern about AI in HR and payroll
Buyers are not resistant to automation. They are conditional about it. In the second wave, 86% say reliability and predictability come first when they weigh new AI features in HR and payroll tools, 11% want a balance, and 4% put new AI capabilities first. Most already automate part of the work, most often payroll, tax, and calculations (34%), and the conditions for going further are clear: 89% raise at least one concern, led by errors, hallucinations, and payroll accuracy (40%), bias and explainability (20%), and data privacy and security (19%).
In the first wave, leaders drew the line at decisions that touch pay, where they wanted approval workflows, explainability, audit trails, and proof before handing over control. The second wave named what that proof looks like: accuracy demonstrated over time (39%), human approval checkpoints and override controls (24%), and testing on their own scenarios or peer evidence (20%). Trust in automation also depends on the data underneath it: 30% say AI would earn more of their trust if it drew on one unified data source, and 16% have already seen data from multiple systems cause errors, inconsistency, or rework in automation. On a unified foundation, security and automation reinforce each other; on a fragmented one, every automated step inherits the risk of the data beneath it.
Trust is earned with proof and oversight: Leaders want AI to prove itself before it touches pay: 39% need accuracy demonstrated over time and 24% want approval checkpoints and override controls. 40% name errors and payroll accuracy as their top AI concern.
Unified data is what makes automation safe: 30% say AI would earn more of their trust if it drew on one unified data source, and 16% have already seen data from multiple systems cause errors, inconsistency, or rework in automation.
Adopt AI human-in-the-loop, not autonomous: approval workflows, exception handling, audit trails, and role-based controls. Start in high-value, lower-stakes use cases to build trust, and ask vendors for the proof second-wave leaders want: accuracy demonstrated over time and testing on your own scenarios. Then weigh the architecture. Automation is only as trustworthy as the data it runs on, and a unified single source of truth is what makes it safe to say yes in the workflows that matter most.
“There's a lot of things that have to be proven to me first. And I would have to have the vendor prove it to me with certainty because people don't like their paychecks being messed up.”
“I want testing on our scenarios, clear audit trails, and human override before AI touches sensitive decisions. Not against it, just want the controls to mature first.”
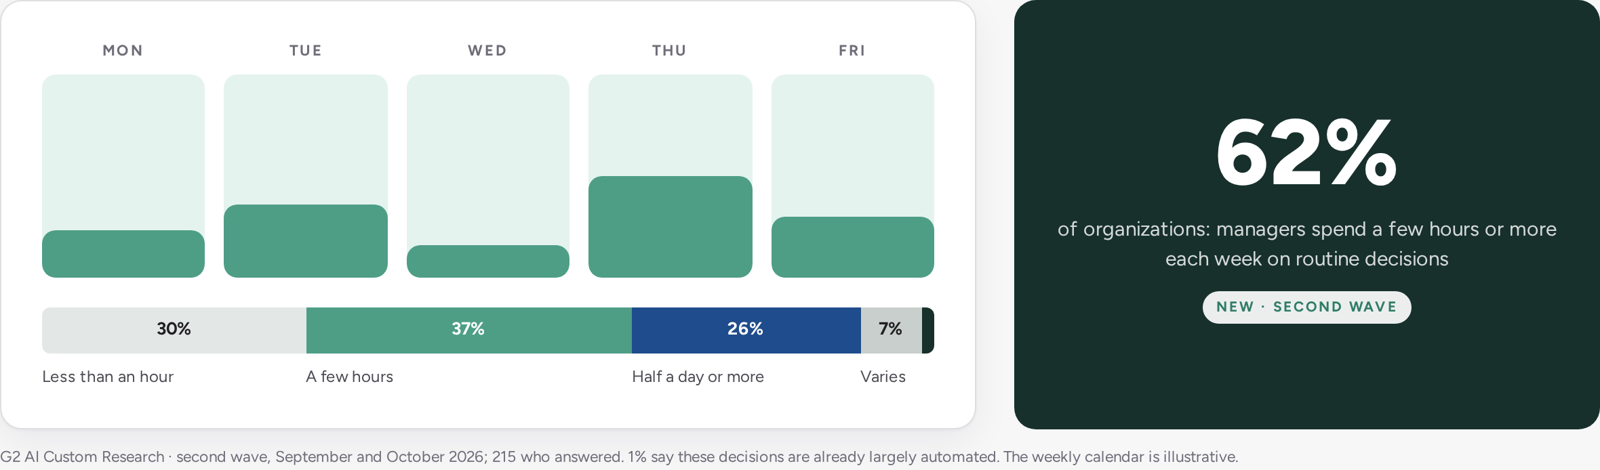
Time-off approvals, payroll exceptions, expense approvals, and employee changes land on managers every week. The second wave measured that load for the first time: at 62% of organizations, managers spend a few hours or more each week on these routine decisions.
name time-off, leave, or time-card approvals
Routine decisions are a steady weekly load on managers. Asked how much time managers spend in a typical week on decisions such as time-off approvals, payroll exceptions, expense approvals, and employee changes, 37% of leaders say a few hours and 26% say half a day or more. 30% say less than an hour, 7% say it varies widely by manager or team, and just 1% say these decisions are already largely automated.
Time-off, leave, and time-card approvals create the most friction (29%), followed by expense approvals (23%), payroll exceptions and corrections (19%), and employee changes and scheduling (17%). Most leaders (61%) call the time reasonable, but 24% say it is too much and another 10% say it could be cut through automation. The heavier the load, the less reasonable it feels: where managers spend half a day or more each week, 47% of leaders say it is too much, against 7% where it takes less than an hour.
Time-off approvals create the most friction: 29% name time-off, leave, or time-card approvals as the routine decision that takes the most time or creates the most friction, ahead of expense approvals (23%), payroll exceptions (19%), and employee changes (17%).
The heaviest loads feel like too much: Where managers spend half a day or more each week on routine decisions, 47% of leaders say it is too much time. Overall, 34% say the time is too much or could be reduced through automation.
Measure the time managers spend on routine approvals before you evaluate any HR and payroll system. Many time-off requests, expense approvals, payroll exceptions, and employee changes follow rules your organization has already written, so ask how much of that work a system can decide consistently on those rules, and how much it sends to a manager only when something falls outside them.
“Probably 50% or more of my time is spent on all of those types of things time off approvals, payroll, expense, employee changes, It's a lot of time.”
“It's too much. Inefficient because it's not just one manager. It's multiple managers. By the time you compound it by the number of managers, you're talking days of wasted time.”
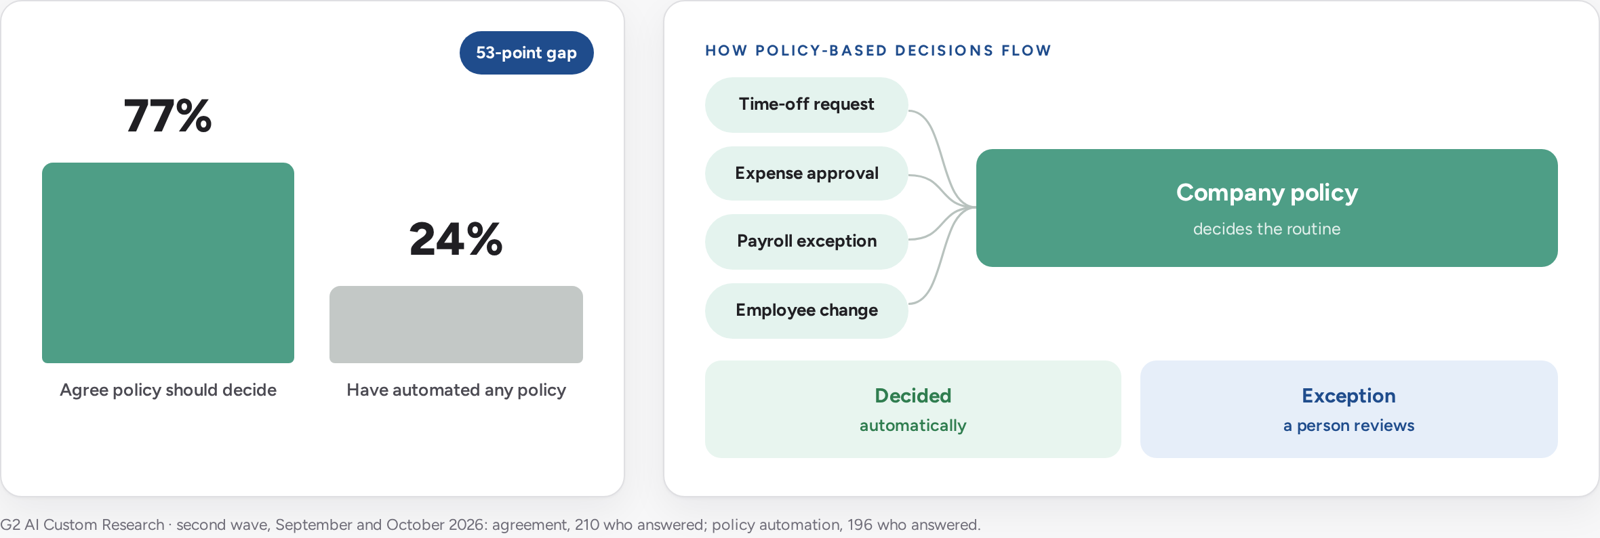
Leaders who want a human on high-stakes decisions are ready to let policy decide the routine. 77% agree routine HR and payroll decisions should be automated whenever company policy clearly defines the outcome, including 57% of those holding back on automation today. Only 24% have done it.
would let clear policy-defined decisions run end to end
The second wave asked a question the first did not: should company policy decide routine decisions? Leaders are ready to let it. 77% agree that routine HR and payroll decisions, such as time-off requests, should be automated whenever company policies clearly define the expected response: 44% strongly and 33% generally. 9% are neutral and 15% lean toward disagreeing or disagree. Support holds even among the cautious: 57% of leaders who are holding back on automation today still agree, and agreement rises with the workload, from 68% where routine decisions take managers less than an hour a week to 91% where they take half a day or more.
Leaders draw the line at exceptions: 33% would let clear policy-defined decisions run end to end, 34% want human review kept for exceptions, high-impact changes, and sensitive cases, and 16% want automation to recommend or route with a person approving. Only 17% want a person involved in every routine people decision. Practice lags behind: only 24% have automated any policy so far, most often for time-off, scheduling, or approvals (17%), and another 7% are piloting or planning it. The 53-point gap between agreement and practice is the clearest opening in the study.
Agreement runs ahead of practice: 77% agree policy-defined decisions should be automated, but only 24% have automated any policy so far, most often for time-off, scheduling, or approvals. Another 7% are piloting or planning it.
Leaders want people on the exceptions: 33% would let clear policy-defined decisions run end to end and 34% would keep human review for exceptions, high-impact changes, and sensitive cases. Just 17% want a person involved in every routine people decision.
Start automating where your policy already decides the answer. Time-off requests, routine approvals, and other decisions with a clearly defined expected response can run automatically, with people reviewing the exceptions. Favor systems with decisioning logic, where you set the rules and keep human oversight while the technology applies them consistently across the organization. Keep humans in control of high-stakes decisions: automation is only as trustworthy as the source of truth it runs on.
“100% agree. As long as it's aligned within the guidelines that we've set as an organization, a manager should never have to touch it.”
“HR and payroll leaders are increasingly looking for software that automates decisions for them. They want to reduce the operational burden created by disconnected systems. They want data consolidation that enables full-solution automation through decisioning logic, reducing manual work, improving accuracy and giving organizations greater confidence in their data. When information flows through a single software, teams can automate routine processes, spend less time reconciling systems and focus more on supporting employees and driving business outcomes.”
Because many organizations operate across fragmented systems with manual reconciliation, buyers assess solutions through a broad total-cost lens that includes support and services. Operational friction does not stay contained at the workflow level; it directly shapes commercial evaluation and perceived value.
For buyers: price the operating burden into every comparison. Integration friction, manual reconciliation, and service dependency are part of a platform's real cost, not just its feature list.
Security confidence and openness to automation both depend on preserved oversight. Buyers trust current environments through internal controls and safeguards, and they extend that same logic to AI by accepting automation only when human guardrails remain in place.
For buyers: hold any new system, and any AI inside it, to the standard you already trust: transparency, approvals, auditability, and a human in the loop.
Although most buyers say switching is feasible, they also describe it as time- and resource-intensive. Combined with a broad total-cost mindset, this suggests that willingness to change exists, but only when the benefits clearly outweigh transition burden and ongoing support demands.
For buyers: make any switch contingent on strong onboarding, implementation support, and proof that total operating burden actually drops over time.
Leaders will not hand consequential decisions to a black box, but they will let their own policies make the routine ones. Where company policy already defines the outcome, agreement to automate is broad, rises with the weekly load, and holds even among those holding back on automation today.
For buyers: start where your policy already decides the answer, and keep people on the exceptions.
It is the norm. Across 428 interviews, 81% of organizations are not on a single unified system. In the second wave, 67% hold people data in two or more systems, 64% need manual work to keep HR and payroll aligned, and at 38% of organizations someone spends a few hours or more every week reconciling data between systems.
Most would. Asked directly in the second wave, 62% would welcome one unified system, including 25% with reservations, and only 6% would prefer to keep separate systems. Among leaders in fragmented multi-system setups, 87% would welcome it.
In fragmented setups. In the second wave, 24% of leaders in fragmented multi-system environments feel exposed, against 2% in partially unified environments and none on a unified single system. The work is constant: 57% still track some regulatory change by hand and 52% manage compliance across several states or countries.
No. About eight in ten take a broad total-cost view that includes implementation, services, and ongoing support. In the second wave, 48% of leaders who could judge a past purchase underestimated its full cost, most often in ongoing support and add-ons or in implementation and internal labor.
Because payroll problems cannot wait in a queue. In the second wave, 74% strongly prefer or consider essential a dedicated contact who knows their account, and 55% have been through generic support that caused delays, repeated explanations, or a missed payroll-critical issue.
Feasible but demanding. Of second-wave leaders who recently led an implementation, 54% met at least one hidden cost and 49% needed more time, staff, or budget than planned, while 66% say the vendor made the move easier or gave strong hands-on support.
Open, on their terms. In the second wave, 86% put reliability and predictability ahead of new AI features and 89% raise at least one concern, led by errors and payroll accuracy. Where company policy already defines the answer, 77% agree routine decisions should be automated.
This was measured only in the second wave. At 62% of organizations, managers spend a few hours or more each week on routine decisions such as time-off approvals, payroll exceptions, expense approvals, and employee changes: 37% say a few hours and 26% half a day or more. Time-off, leave, and time-card approvals create the most friction (29%).
77% of second-wave leaders agree, 44% strongly, and only 15% lean toward disagreeing or disagree. Most want people kept on exceptions rather than on every decision: just 17% want a person involved in every routine people decision. Only 24% have automated any policy so far, and 57% of those holding back on automation still agree.
You are already paying a fragmentation tax in manual work, reconciliation, and risk. Compare platforms on how much of that burden they remove, not on feature checklists. That is the problem most worth solving. Evidence: 64% of second-wave leaders need manual work to keep HR and payroll aligned; at 38% of organizations it takes a few hours or more every week.
A single unified system, one database for HR, payroll, time, and benefits, cuts manual work, shrinks the compliance and security surface, and removes the gaps where data goes wrong. Weigh it as a risk decision, not a feature upgrade. Evidence: 81% of 428 leaders are not on one system; in the second wave, 24% of leaders in fragmented setups feel exposed on compliance, against none on a unified system.
Start with routine decisions that have a clearly defined expected response, such as time-off requests and standard approvals. Set the rules yourself, let the system apply them consistently, and route the exceptions to a manager. Evidence: 77% agree policy-defined decisions should be automated; only 24% have done it; agreement reaches 91% where the weekly load is heaviest.
Switching is feared because HR and payroll touch every employee. De-risk it directly: require a structured implementation program, a dedicated team that owns the move, and explicit continuity safeguards for pay and benefits. Evidence: 54% of recent implementers met hidden costs and 49% needed more time, staff, or budget; 66% say vendor support made the move easier.
Do the all-in math: implementation, services, configuration, and ongoing support, not just the subscription line. Expect continuous, named support to be part of the value, not an upsell. Evidence: About eight in ten take a broad total-cost view; 74% of second-wave leaders want a dedicated contact; 55% have been slowed by generic support.
Keep humans in control of high-stakes decisions and let automation prove its accuracy in lower-stakes workflows first. Then weigh the architecture: automation is only as trustworthy as the source of truth it runs on. Evidence: 86% put reliability first, 89% raise at least one concern, and 30% say one unified data source would earn more trust.
G2 Research
G2 is the world's largest and most trusted software marketplace. G2 AI Custom Research builds original studies from real buyer interviews, conducted by G2's AI interviewer and reviewed by G2's research team. This report combines two waves of The New Buying Logic for HR and Payroll, June to October 2026, 428 interviews in all.
This research combines two waves of G2 AI Custom Research on HR and payroll buying logic, both commissioned by Paycom: 211 in-depth interviews in June 2026 and 217 in September and October 2026, 428 in all.
The first wave drew on business professionals across technology, financial services, healthcare, manufacturing, and retail, from small businesses to large enterprises, all selected for direct experience with software evaluation, implementation, integration, and operational risk management.
The second wave drew on HR, payroll, finance, IT, and executive leaders at US organizations. Participants were screened for roles with responsibility for HR, payroll, or HCM technology and for owning or significantly influencing those decisions; consultants and advisors were excluded. Interviews lasted 10 to 70 minutes, 37 minutes on average. The guide repeated the first wave's questions and added two: how much time managers spend each week on routine workforce decisions, and whether routine HR and payroll decisions should be automated whenever company policy clearly defines the outcome.
In both waves, G2's AI interviewer conducted the conversations in an open format so leaders could describe their actual systems, costs, and attitudes rather than select from preset options. Transcripts were analyzed with AI for semantic understanding, with multi-iteration validation and cross-verification, and reviewed by G2's AI Custom Research team. Each answer was assigned to one category per question. Figures are percentages of the respondents who answered each question; follow-up questions put only to a subgroup, such as leaders who recently led an implementation, are based on that subgroup. Figures are rounded and may not total exactly 100%. Quotations are verbatim and attributed by role and industry.
The two waves interviewed different people. Two figures draw on both waves because both asked the question the same way, with the same answer categories: the share on a single unified system, pooled across all 428 interviews (83 of 428, or 19%), and the broad total-cost view (164 of 211 in the first wave and 168 of 204 in the second, about eight in ten in each). All other figures come from the second wave alone.
G2 Research, October 2026
This report was originally published in June 2026, updated in August 2026, and refreshed with a second wave of research in October 2026.
About this research
428 Interviews · 2 Waves · 2026 Research Year
Respondent roles · second wave: Executive owner or C-suite 25% · HR, people, and payroll leadership 23% · Finance and operations leadership 22% · HR, payroll, or tech practitioner 15% · IT and HRIS leadership 14%
Company size · second wave: Fewer than 50 employees 30% · 50 to 249 24% · 250 to 999 19% · 1,000 to 9,999 17% · 10,000 or more 11%
Industries · second wave: Manufacturing, retail, transportation, public sector 43% · Professional services, legal, nonprofit 19% · Healthcare, life sciences, social services 17% · Technology, software, telecommunications 12% · Financial services, insurance, real estate 9%
Shares of second-wave respondents who answered each question (role 214, company size 206, industry 213). Role is by function; by level, 48% hold C-level, owner, or executive roles.
AI-conducted voice interviews · Primary research · Exclusive first-party data
Sponsored
Paycom provides a single software for HR and payroll, eliminating the burden of managing multiple disconnected systems.
With Paycom, you get one unified platform that handles payroll, HR, talent acquisition, talent management, and time and labor management—all in a single database. Join the organizations that have eliminated manual reconciliation and reduced operational risk.
Paycom provides a cloud-based HCM solution delivered as a single application, eliminating the need for multiple systems and manual data transfers. With industry-leading employee self-service, Paycom empowers organizations to reduce administrative burden while improving accuracy and compliance.
This research was commissioned by Paycom. G2 maintains full editorial independence.
Commission Research
Partner with G2 Research on an original study built from real buyer interviews and structured for AI citation.
Explore more original research, selected from our latest reports.
How 100 UK business decision-makers experience technology fragmentation and AI readiness: 77% run on estates where 60% or less of software is connected, 90% flag security or compliance exposure, only 7% can quantify AI financial return, and 73% call becoming a connected organisation business-critical.
G2 Research's 2026 study of 549 professionals finds 70% of product roadmaps now bend toward AI, but most still have not settled on how to charge for it.
G2 research from 1,392 interviews finds 77% of professionals embed AI in workflows, while governance, readiness, and work redesign lag behind.